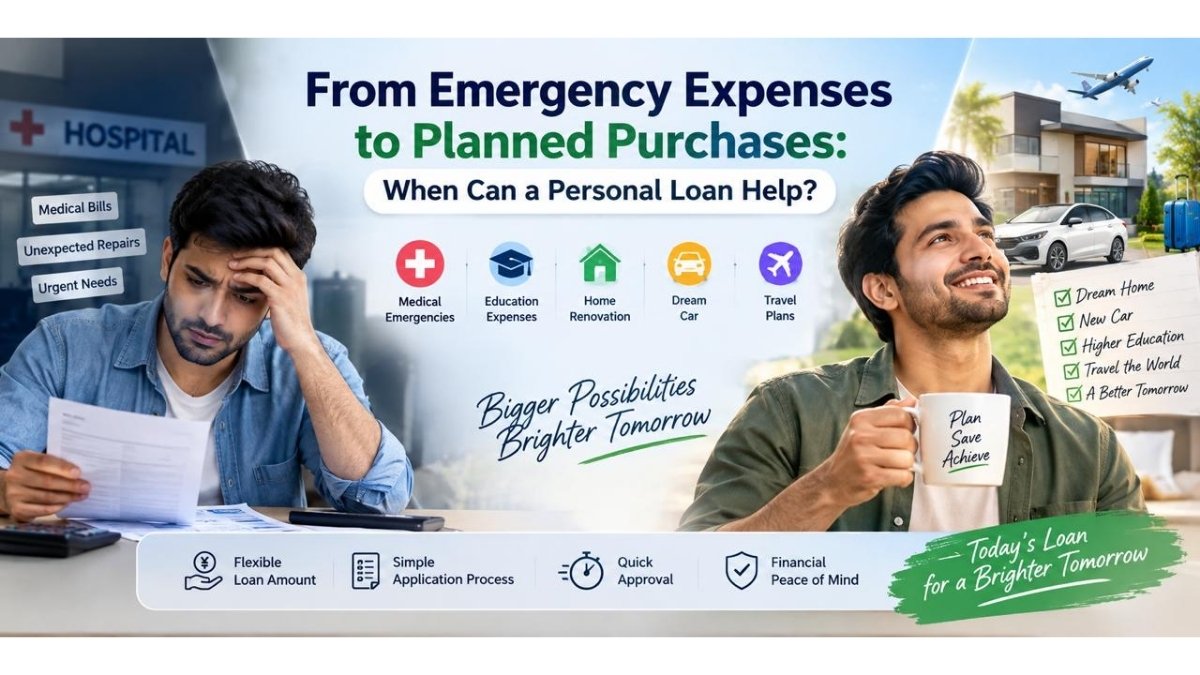
New Delhi [India], October 5: Financial needs do not always arrive at a convenient time. A sudden medical bill, urgent home repair or unexpected family expense can require funds immediately. At other times, you may be planning an expense such as renovating your home, paying for a course or making a significant purchase.
Quick Overview
- A personal loan can help manage urgent expenses when you need funds without pledging an asset as collateral.
- It can also be used for planned expenses such as home improvements, education-related costs, travel, or large purchases.
- Since it is generally an unsecured personal loan, the lender usually evaluates factors such as income, credit history, age, and repayment capacity.
- Before applying, compare the personal loan interest rate, processing fee, tenure, EMI and other applicable charges.
- Use a personal loan EMI calculator to estimate your monthly repayment and assess whether it fits your budget.
- Avoid borrowing for expenses that can be postponed or when the EMI could put significant pressure on your monthly finances.
A personal loan can be considered in both situations because it can provide access to funds without requiring the borrower to pledge an asset as collateral. However, borrowing should be based on your financial capacity rather than simply the availability of credit.
Understanding when a personal loan can be useful, how much you can comfortably repay and what charges apply can help you make a more informed borrowing decision.
When Can a Personal Loan Be Useful?
A personal loan may be useful when you have a genuine financial requirement and need a structured way to fund it. Since personal loans are generally unsecured, you do not typically need to provide collateral such as property or gold.
Some situations where borrowers may consider a personal loan include:
- Medical or other urgent expenses
- Home repairs or renovation
- Education-related expenses
- Wedding expenses
- Planned travel
- Large household purchases
- Consolidating certain existing debts, subject to financial suitability
The right borrowing option depends on the nature and urgency of the expense. For example, if you are planning an expense several months in advance, saving towards it may be another option worth considering.
Your personal loan eligibility will also depend on the lender’s criteria. Factors such as age, income, employment or business profile, credit history and existing financial commitments may be considered.
Using a Personal Loan for Emergency Expenses
Emergencies can create financial pressure because the expense may be unavoidable and difficult to postpone. If you do not have enough readily available savings, a personal loan may be one way to meet the requirement.
For instance, an unexpected medical expense or urgent home repair could require a substantial amount at short notice. A personal loan can provide a predetermined amount that can then be repaid through EMIs over an agreed tenure.
However, it is important to consider the total borrowing cost before applying. The personal loan interest rate, processing fee and other applicable charges can affect the overall amount you repay.
Before taking a loan for an emergency, consider:
- The amount you actually need: Borrow only what is required rather than taking a larger amount simply because you are eligible for it.
- Your repayment capacity: Check whether the EMI can be accommodated alongside rent, household expenses, existing EMIs and savings.
- The total cost: Look beyond the interest rate and check processing fees and other applicable charges.
- The repayment period: A longer tenure can reduce the monthly EMI but may increase the total interest payable.
An emergency does not eliminate the need to assess affordability. Taking a loan that you cannot comfortably repay could create additional financial stress after the immediate problem has been addressed.
Can a Personal Loan Help With Planned Expenses?
A personal loan can also be considered for planned expenses when you need funds before you have accumulated sufficient savings. The key is to evaluate whether borrowing is financially practical.
For example, you may be planning a home renovation or a significant household purchase. Instead of paying the entire cost from your available savings, you may consider financing part of the expense through a personal loan.
However, planned expenses give you more time to compare alternatives. You could potentially save for the expense, reduce the purchase amount, or explore a loan product specifically designed for that purpose.
Consider the following before borrowing:
| Consideration | What to assess |
| Urgency | Can the purchase be postponed? |
| Amount required | Do you need to finance the entire expense? |
| Savings | Can you pay part of the cost from existing savings? |
| EMI | Can you comfortably manage the monthly repayment? |
| Total cost | What will you repay after interest and applicable charges? |
For planned purchases, borrowing should ideally fit into your broader financial plan rather than becoming a substitute for regular saving.
How to Decide If You Can Afford a Personal Loan?
Affordability is not determined only by whether you meet the lender’s personal loan eligibility criteria. A lender’s approval indicates that you meet its requirements; it does not necessarily mean that the EMI will be comfortable for your personal budget.
Start by calculating your monthly income and regular expenses. Include existing loan EMIs, rent, utility bills, insurance premiums, household expenses and other recurring commitments.
You can then use a personal loan EMI calculator to estimate the EMI for different loan amounts, interest rates and tenures. This can help you understand how changing the loan amount or repayment period affects your monthly obligation.
Before proceeding, ask yourself:
- Will the EMI remain manageable if my monthly expenses increase?
- Do I have sufficient emergency savings?
- Am I already repaying other loans?
- Does the expense justify taking on additional debt?
- Can I continue meeting my regular savings goals after paying the EMI?
A practical assessment should account for both the immediate expense and your ability to manage repayments throughout the loan tenure.
What to Check Before Choosing a Personal Loan?
Once you decide that borrowing may be suitable, compare the terms rather than focusing on the approved loan amount alone.
Personal Loan Interest Rate
The interest rate directly affects the cost of borrowing. Compare the applicable personal loan interest rate and understand whether the rate and repayment terms offered suit your financial situation.
Processing Fee
Lenders may charge a personal loan processing fee for processing and disbursing the loan. Check the applicable fee and whether taxes or other charges apply.
Loan Tenure
A longer tenure may result in a lower monthly EMI, while a shorter tenure may mean higher monthly repayments. Compare the total repayment amount under different tenure options.
EMI and Repayment Schedule
Make sure you understand the EMI amount, repayment frequency and due dates. Missing repayments can have financial consequences, including additional charges and potential impact on your credit profile.
Eligibility Requirements
Check the lender’s personal loan eligibility criteria before applying. Requirements may include minimum income, age, employment or business profile, residence, credit history and other conditions.
Other Terms and Charges
Read the loan documentation carefully and check for applicable charges related to late payments, foreclosure, partial prepayment, or other services, as applicable.
When Should You Avoid Taking a Personal Loan?
A personal loan may not be suitable in every situation. Consider avoiding or postponing borrowing when:
- The purchase is non-essential and can easily be delayed.
- You already have several outstanding loans or high monthly obligations.
- The proposed EMI would leave very little room for essential expenses.
- You are borrowing primarily to fund recurring monthly expenses.
- You have not compared the total cost of borrowing.
- You can comfortably meet the expense by using savings without significantly affecting your emergency fund.
- You are considering taking a new loan to repeatedly manage existing debt without addressing the underlying cash-flow issue.
Borrowing for one expense can also affect your ability to take care of future financial requirements. Therefore, consider both your current need and your longer-term financial commitments before making a decision.
Conclusion
A personal loan can be considered for both unexpected emergencies and planned expenses, provided the borrowing requirement is genuine and the repayment fits comfortably within your budget. Comparing the personal loan interest rate, processing fee, tenure and other applicable charges can help you understand the overall cost.
Before applying, check your personal loan eligibility and use a personal loan EMI calculator to estimate the monthly repayment. Most importantly, borrow only an amount that you can reasonably repay while continuing to manage your essential expenses and financial goals.
FAQs
What expenses can a personal loan be used for?
A personal loan can generally be used for various personal requirements, such as medical expenses, home renovation, education-related costs, weddings, travel or significant household purchases, subject to the lender’s terms and conditions.
When should I consider taking a personal loan for an emergency expense?
You may consider a personal loan when an urgent expense cannot be postponed, your available savings are insufficient, and you have adequate repayment capacity. Compare the loan cost and EMI before applying.
Can I use a personal loan for planned purchases?
Yes, a personal loan can be used for eligible planned personal expenses. However, compare the cost of borrowing with alternatives such as saving for the purchase or using a suitable purpose-specific loan.
How do I know if I can afford a personal loan?
Review your income, essential expenses, existing EMIs and savings before borrowing. You can also use a personal loan EMI calculator to estimate the monthly repayment for different loan amounts, interest rates and tenures.
What should I check before applying for a personal loan?
Check the personal loan interest rate, processing fee, tenure, EMI, eligibility requirements, repayment terms and other applicable charges. Also assess whether the proposed EMI fits comfortably within your monthly budget.
If you object to the content of this press release, please notify us at [email protected]. We will respond and rectify the situation within 24 hours.